What's happening? Popular, Inc., First BanCorp. and OFG Bancorp (Oriental) grew their loan portfolios (the total amount they have lent to their customers) during the third quarter of 2026 (July through September). Business loans were one of the main drivers of that growth.
Their executives highlighted the stability of Puerto Rico's economy, supported by the labor market and business activity. But they also acknowledged challenges tied to inflation, interest rate volatility, and high fuel and energy costs, which continue to affect consumers and businesses.
Why does it matter? Bank loans finance everything from home and vehicle purchases to business expansion. The growth of these portfolios offers a look at how much money is being lent in Puerto Rico and which sectors it is moving toward.
Ganancia neta. Lo que le queda al banco después de restar todos sus gastos, incluidos los impuestos.
Ganancia por acción. De esa ganancia, cuánto le corresponde a cada acción de la empresa.
Ingresos netos por interés. El margen entre lo que el banco cobra por el dinero que presta y lo que paga a quienes guardan dinero en sus cuentas.
Originación de préstamos. Préstamos nuevos otorgados durante el trimestre. No incluye los que fueron aprobados pero no se desembolsaron.
Depósitos. El dinero que clientes, empresas y entidades públicas guardan en el banco.
Préstamos morosos. Préstamos cuyos pagos están atrasados.
Recompra de acciones. Cuando la empresa compra de vuelta sus propias acciones. Es una de las formas en que le devuelve dinero a sus accionistas.
Financial results table
Resultados financieros
Bancos comerciales de Puerto Rico: tercer trimestre 2026
| Métrica | Popular, Inc. | First BanCorp. | OFG Bancorp (Oriental) |
|---|---|---|---|
| Ingresos netos | |||
| Ingresos netos | $266.3 millones | $96.1 millones | $56.6 millones |
| Comparación con trimestre anterior | -$11.9 millones | -$39,000 | -$2.2 millones |
| Comparación con Q3 2025 | +$55 millones | -$4.4 millones | +$4.8 millones |
| Equivalencia en acción diluida (EPS) | |||
| Equivalencia en acción diluida (EPS) | $4.21 | $0.63 | $1.33 |
| EPS del trimestre anterior | $4.35 | $0.62 | $1.39 |
| EPS del año anterior | $3.14 | $0.63 | $1.16 |
| Ingresos por interés netos | |||
| Ingresos por interés netos | $698.9 millones | $227.5 millones | $153.6 millones |
| Comparación con trimestre anterior | +$5.5 millones | -$1.6 millones | -$3.7 millones |
| Comparación con Q3 2025 | +$52.4 millones | +$9.6 millones | -$1.2 millones |
| Margen de interés neto | 3.63% | 4.73% | 5.23% |
| Cartera total de préstamos al cierre | |||
| Cartera total de préstamos al cierre | $40,043 millones | $13,400 millones | $8,448 millones |
| Comparación con trimestre anterior | +$293 millones | +$108.3 millones | +$151 millones |
| Originación de nuevos préstamos | — | $1,500 millones | $693.8 millones |
| Comparación con trimestre anterior | — | -$238.5 millones | -$61.2 millones |
| Gastos operacionales o no relacionados con intereses | |||
| Gastos operacionales o no relacionados con intereses | $505.6 millones | $130.2 millones | $96.3 millones |
| Comparación con trimestre anterior | +$21.5 millones | +$2.9 millones | -$6.6 millones |
| Saldos de depósitos | |||
| Saldos de depósitos | $68,705 millones | $16,918.6 millones | $9,980 millones |
| Comparación con trimestre anterior | -$1,528 millones o 2%; si se excluyen los depósitos del sector público de Puerto Rico, los depósitos de los clientes disminuyeron en $289 millones o un 1%. | +$49.1 millones; los depósitos principales aumentaron $120.4 millones, impulsados por un alza de $253 millones en depósitos a plazo fijo, parcialmente compensada por una reducción de $132.6 millones en depósitos sin vencimiento fijo. Por su parte, los depósitos gubernamentales disminuyeron $76.7 millones, hasta $3,000 millones, principalmente en Puerto Rico ($57.2 millones) y las Islas Vírgenes ($34.6 millones). | +$58 millones en depósitos totales promedio; aunque los depósitos de clientes al cierre del trimestre bajaron $79.9 millones (0.8%) por reducciones en cuentas a la vista y de ahorro. |
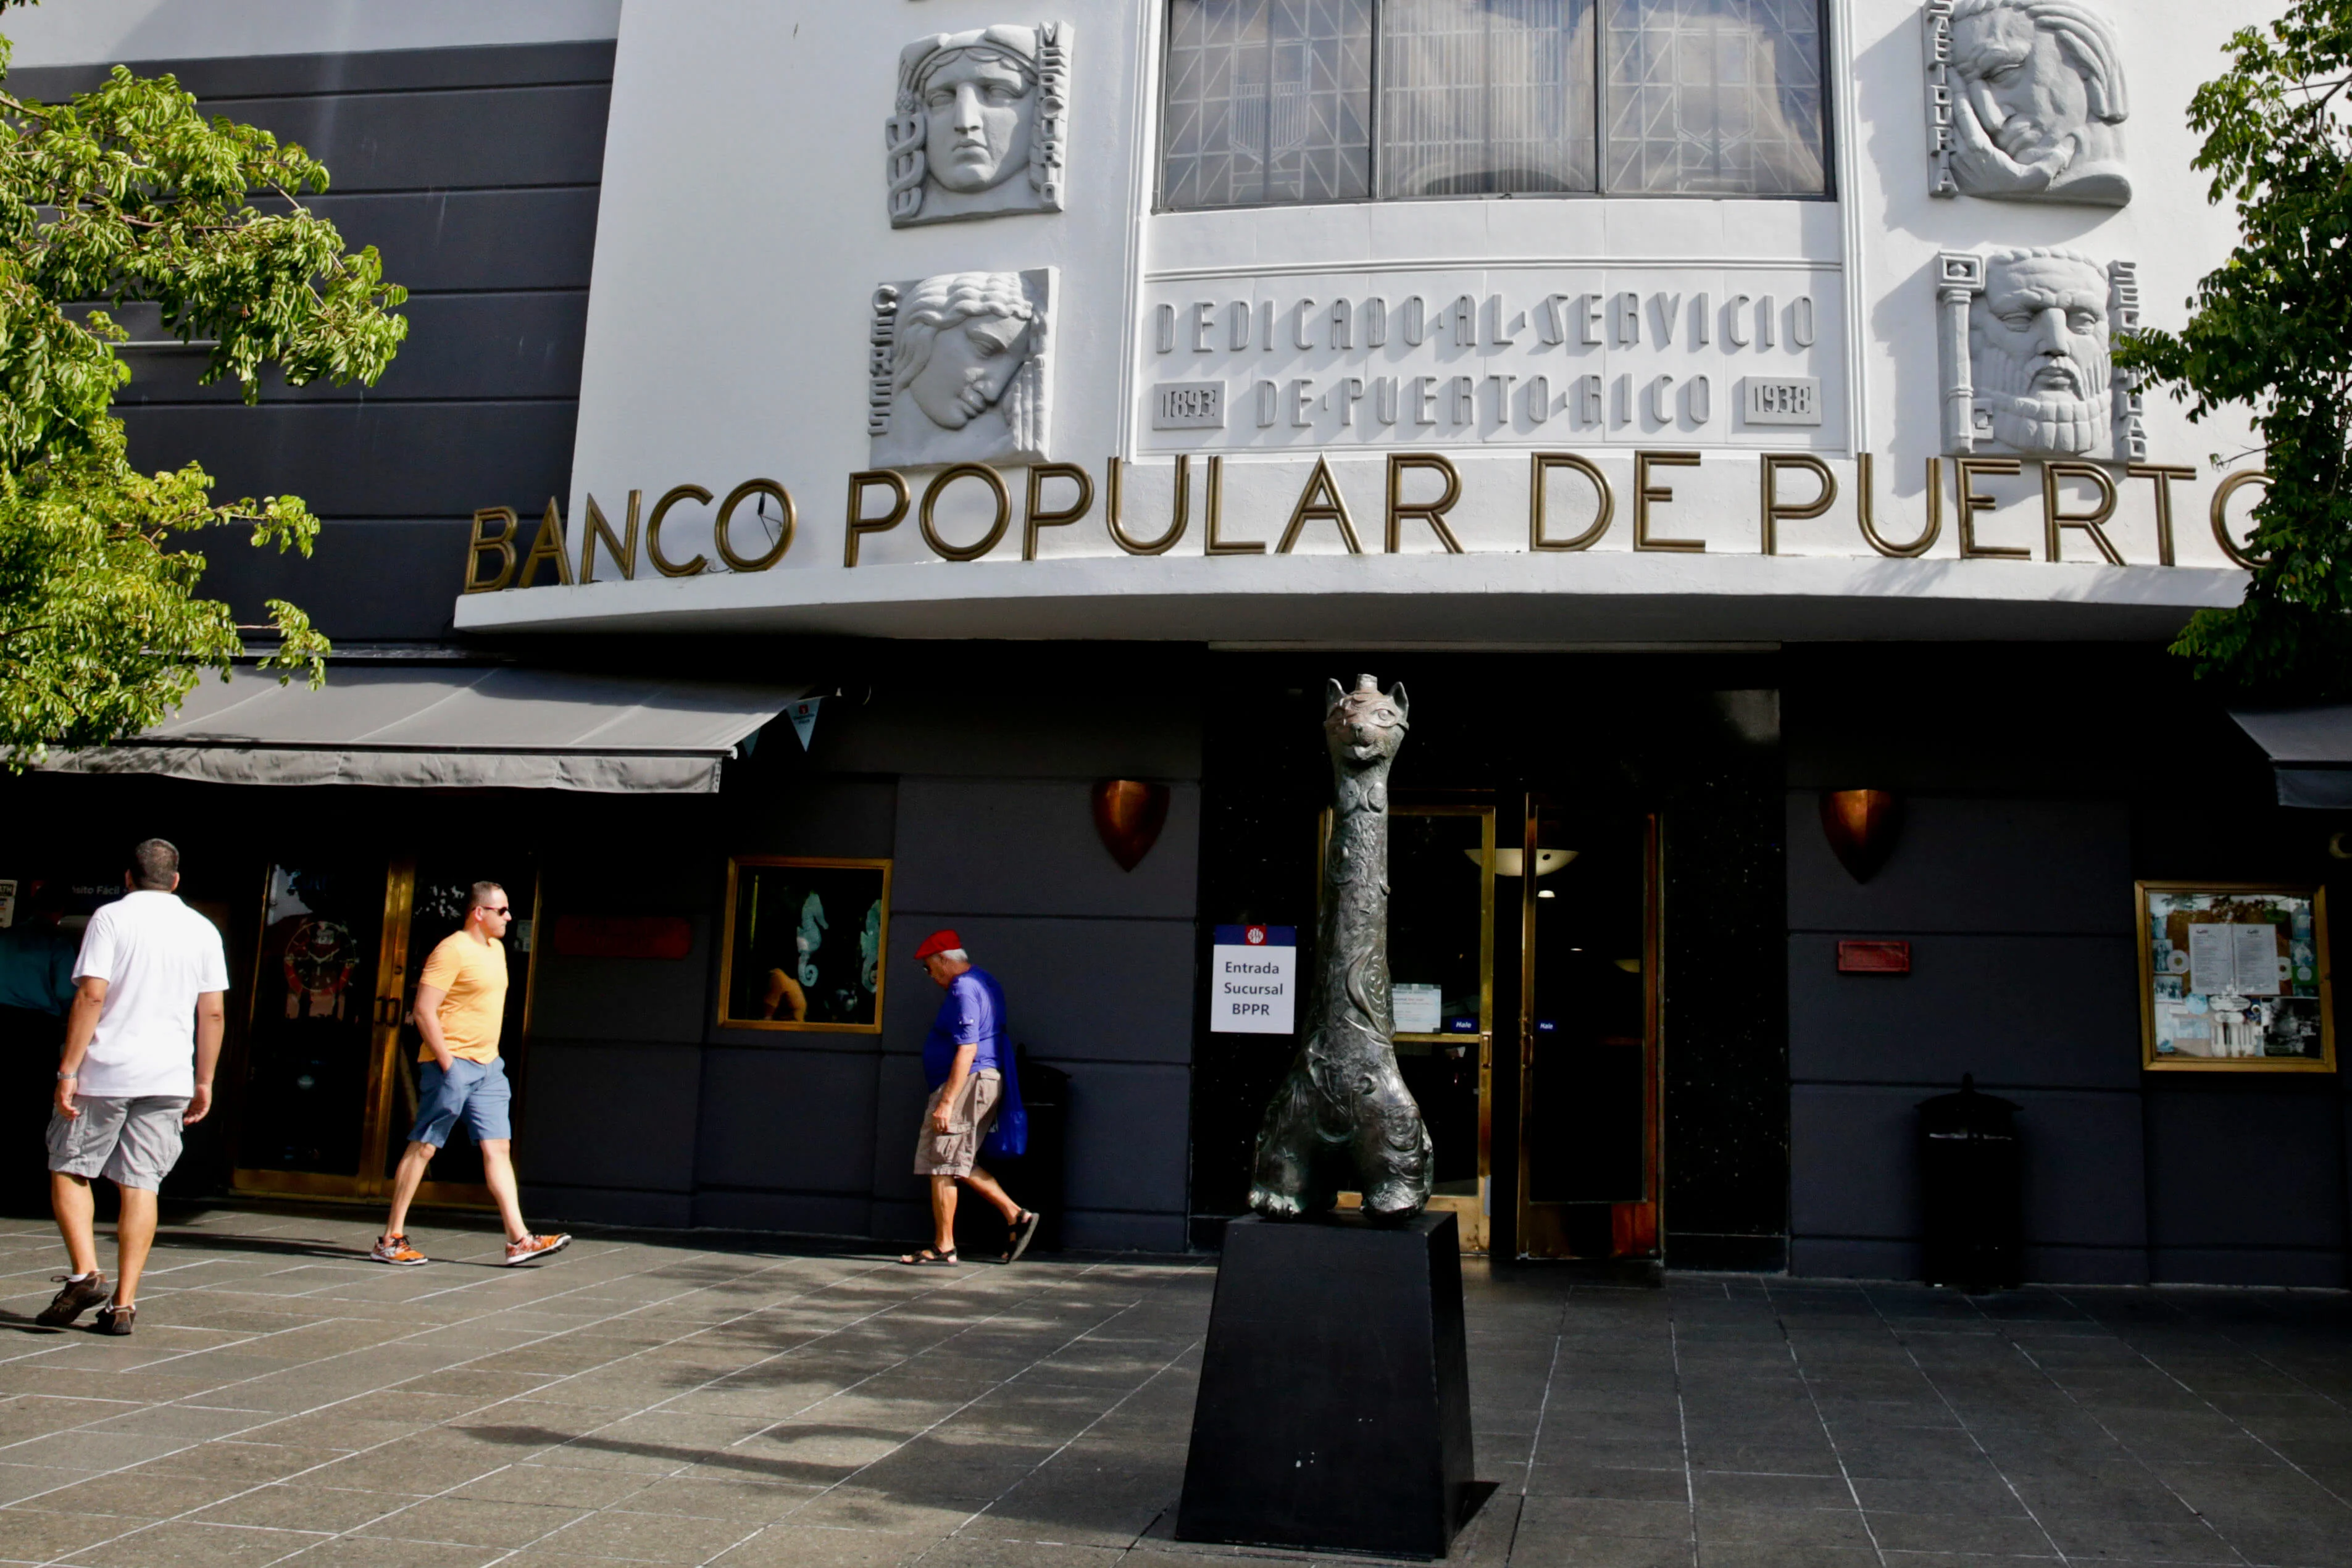
Popular: "Another solid quarter"
Popular, Inc. closed the third quarter of 2026 with a net income of $266.3 million, an increase of 26% compared to the same period in 2025. Compared to the second quarter, earnings fell 4.3% ($11.9 million less).
Its loan portfolio grew $293 million, surpassing $40,000 million, driven by commercial and mortgage loans.
"We reported another solid quarter," said Jorge J. García, president and chief executive officer (CEO) of Popular, Inc., at a roundtable with journalists. "EPS (diluted earnings per share) increased 34% (compared to the prior year). ROTC, which is the return on our tangible capital, was 15.8% and in line with our expectations." In other words, the bank earned more per share held by investors and achieved a solid return on its own capital.
Loans. The portfolio increased $293 million, to $40,043 million, driven by commercial and mortgage lending in Puerto Rico and the United States. In Puerto Rico, all portfolios grew except auto loans, amid a roughly 14% decline in new vehicle sales.
Vivienda Joven: Popular ha otorgado alrededor de $13 millones en préstamos para 75 jóvenes entre 21 a 35 años.
Pronto pa’ tu casa: A través de Popular, se han otorgado $10 millones en esta ayuda para 59 familias.
Deposits. Money deposited at the bank fell $1,528 million compared to the previous quarter, mainly because the Puerto Rico government has fewer funds on deposit. García explained that part of that decline is due to pension payments from the central government.
Credit quality. The provision for credit losses, the money the bank sets aside in case some loans are not repaid, decreased approximately $7 million compared to the second quarter, in a context that García described as one of stable credit quality indicators.
Shareholders. Popular repurchased $179 million in common shares during the quarter and raised its dividend by 20%, with payment taking effect on Oct. 1.
Puerto Rico's economy. "Overall, Puerto Rico's economic environment remains stable, supported by a healthy labor market, tourism, infrastructure investment and private-sector development," García said. Although some indicators "have moderated," he noted that employment reached "its highest level" in the third quarter.
He also pointed out that they are monitoring "pressures driven by inflation and rising fuel and energy costs in Puerto Rico," which are affecting residents.
Digital channel. Active users of Mi Banco, Popular's app, increased 4% compared to last year. The bank continues to develop tools for customers to handle their transactions online.
Card use. García noted that debit card sales increased more than 10% and credit card sales around 9% compared to the same quarter of 2025. He also pointed out that customers are making more transactions, but at a lower average value.
Mi cuenta: Integra secciones de cheques y ahorros en una sola cuenta. Ofrece $0 en cargos por servicio mensual para clientes que reciben depósito directo, mantienen un balance promedio mensual combinado de $500 o tienen menos de 26 años.
Mi Cuenta Uni: Dirigida a jóvenes de 18 a 25 años, no cobra cargos por servicio e incluye beneficios y herramientas que apoyan el manejo responsable del dinero y promueven el ahorro desde una etapa temprana.
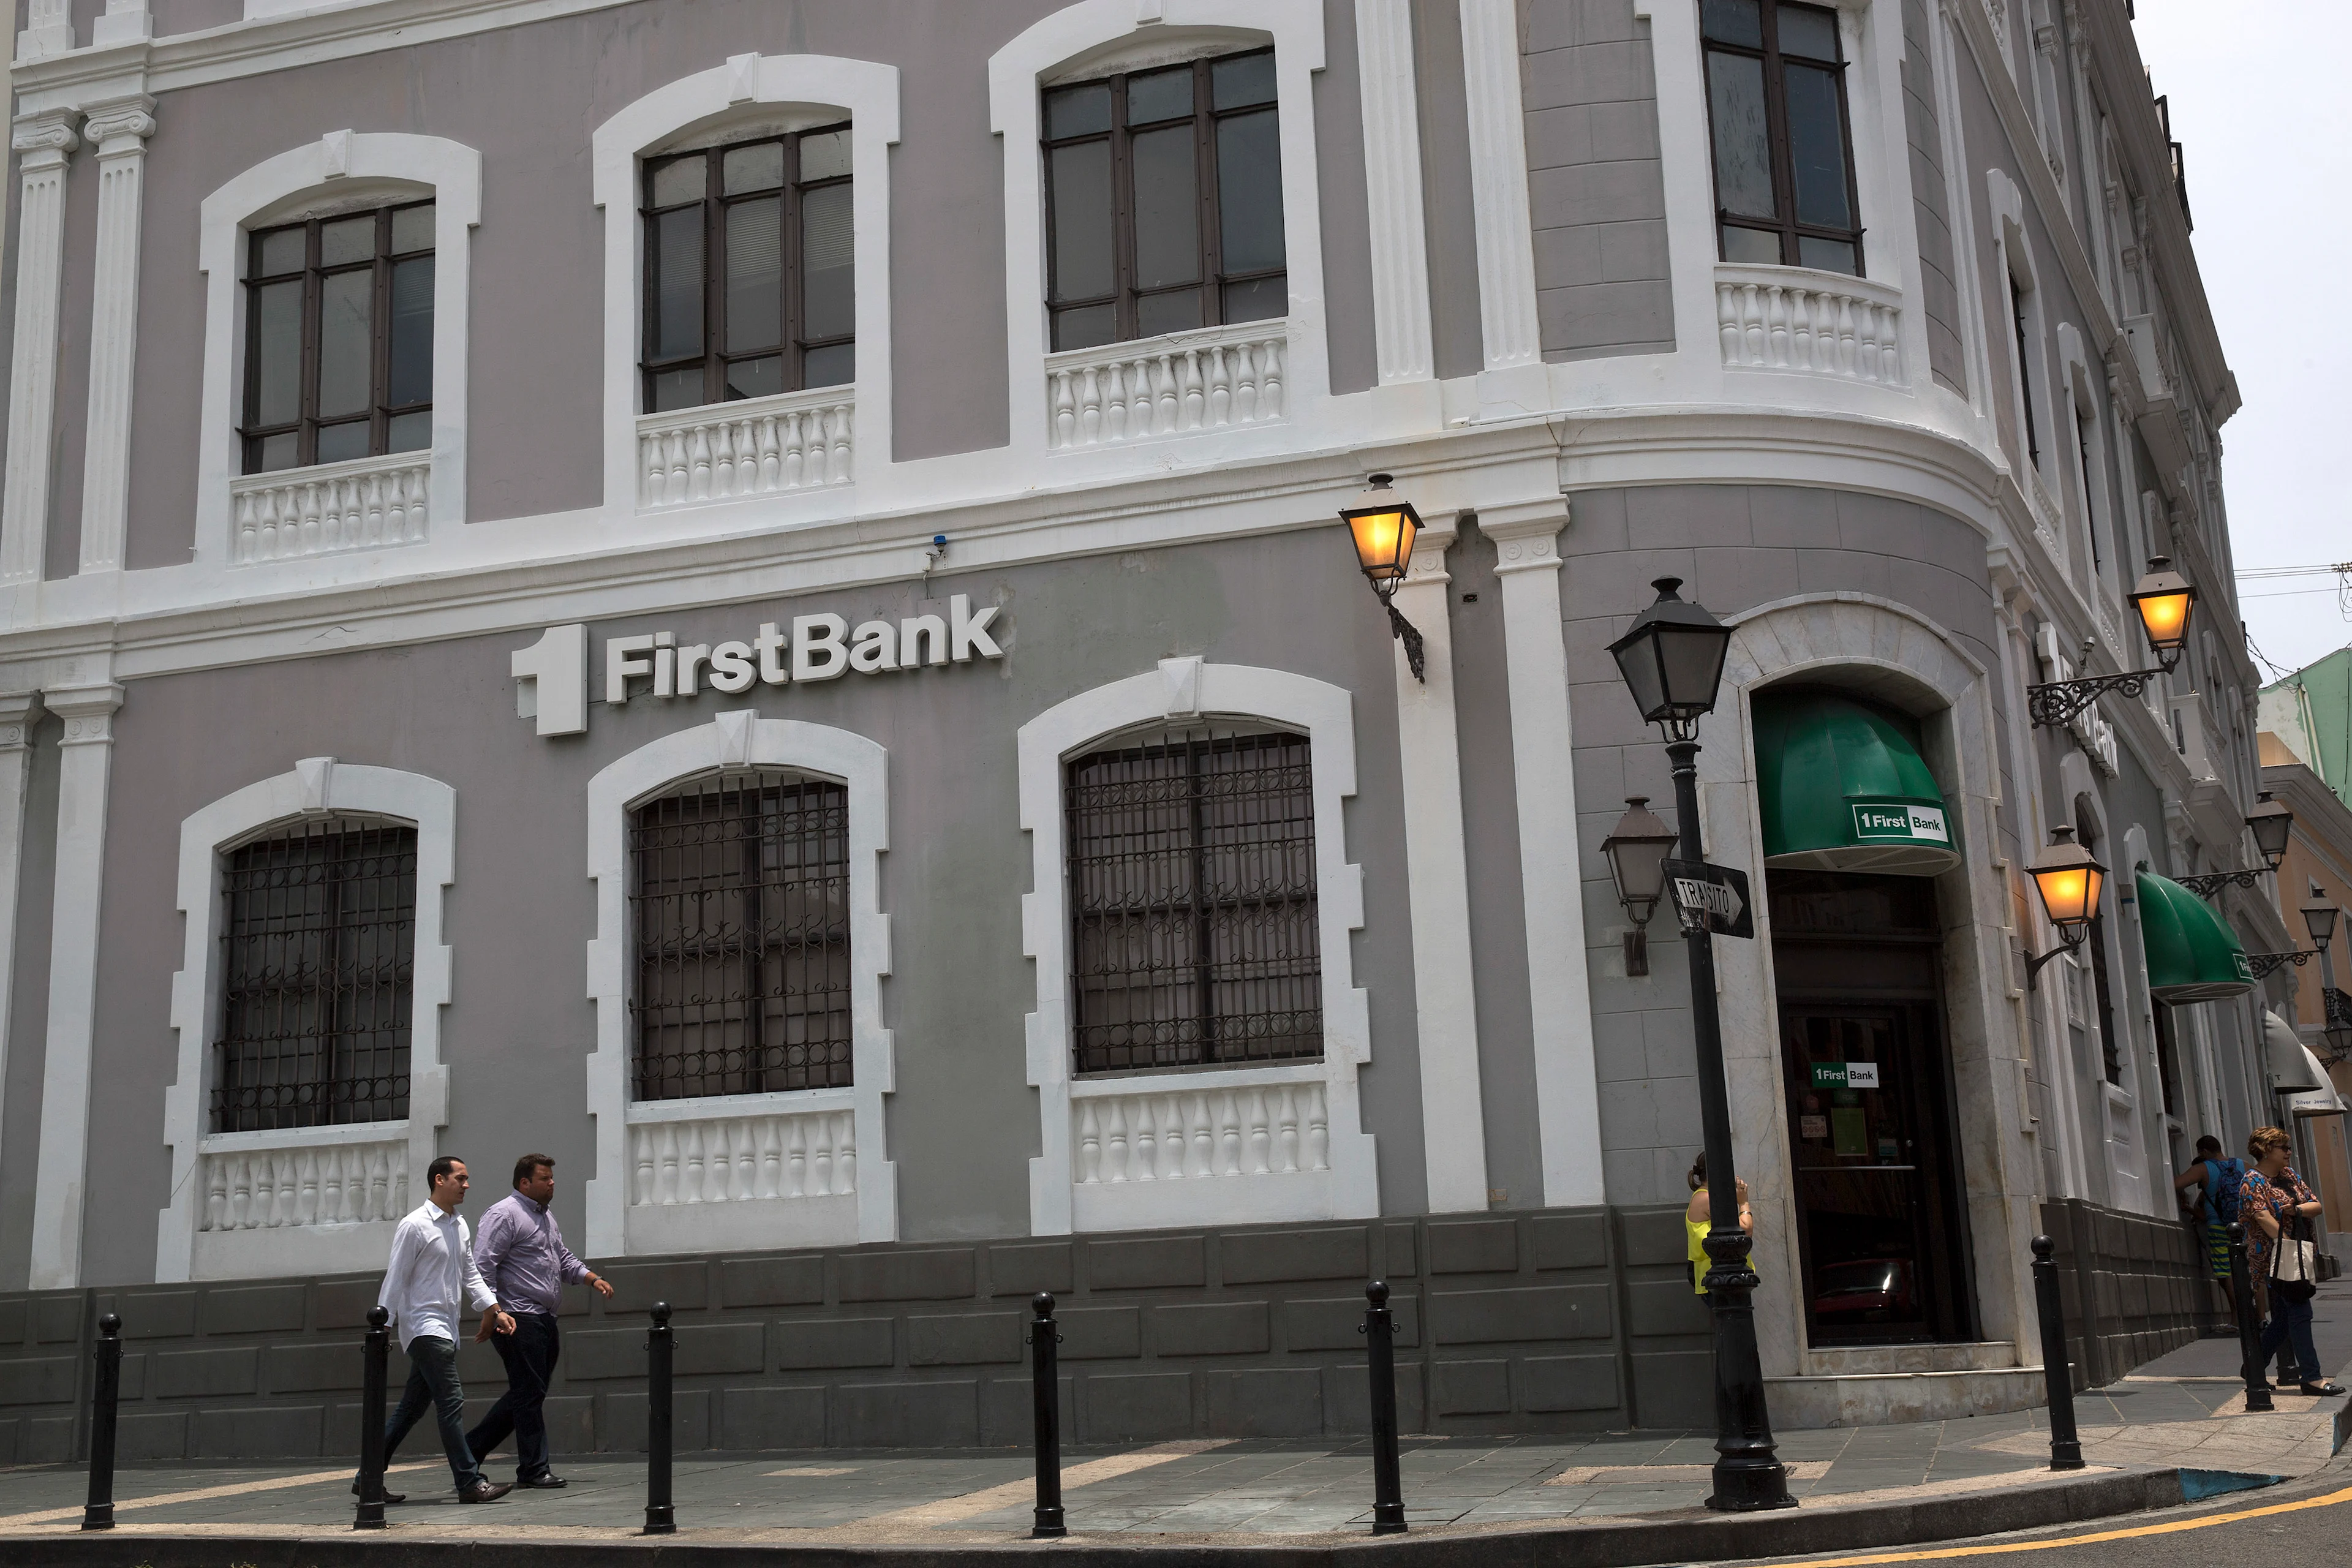
FirstBank: "Another quarter of solid operating performance"
First BanCorp., the parent company of FirstBank, closed the third quarter of 2026 with a net income of $96.1 million, nearly equal to the previous quarter's figure, though 4.4% below the $100.5 million recorded in the same period of 2025.
"We delivered another quarter of solid operating performance," said First BanCorp. President and CEO Aurelio Alemán in a statement. He noted that the bank posted a return of 1.98% on its assets, a measure of how much it earns relative to everything it owns. He also highlighted that customers continue to make payments steadily and that loans grew across all its markets, especially business loans.
Loans. The portfolio grew $108.3 million, driven by commercial and industrial lending. However, the bank originated $238.5 million less in new loans than in the previous quarter. This is mainly because the second quarter included $270.6 million in one-time refinancings that did not recur this time.
Credit quality. The provision for loan losses decreased from $17.3 million to $14.6 million, primarily due to lower estimated losses on residential mortgage loans, following an update to the historical data used to calculate them.
Deposits. Core deposits, which exclude government and brokered deposits, increased $120.4 million. The increase came mostly from certificates of deposit (fixed-term). Government deposits, on the other hand, fell $76.7 million.
Share repurchase. Alemán highlighted the Board of Directors' approval of a $350 million share repurchase program through 2027, which adds to the one announced in October 2025, of which $38.3 million remains.
Dividends. The bank also approved a 25% increase in its quarterly dividend, the payment its shareholders receive. It is part of its strategy of returning capital to shareholders without affecting its growth plans.
Oriental: "Another solid quarter"
OFG Bancorp, the parent company of Oriental Bank, earned $56.6 million in the third quarter of 2026, 9.2% more than the $51.8 million from the same period of 2025. Its earnings per share rose from $1.16 to $1.33, up 14.7% from a year ago.
"We have delivered another solid quarter," said OFG Bancorp CEO José Rafael Fernández. "Our results reflect sustained momentum in commercial loan growth, stable credit quality, solid core deposit balances, disciplined expense management and healthy profitability."
Puerto Rico's economy. "Remains stable, supported by a healthy labor market and the continued expansion of both local companies and those coming from the continental United States," Fernández said.
Loans. The total portfolio grew $151 million (1.8%), to $8,448 million, driven by business and consumer loans in Puerto Rico. The bank originated $693.8 million in new loans. That is $61.2 million less than the previous quarter, but more than in the same period last year.
Deposits. Total deposits, which include customer and brokered deposits, increased $5.8 million, to $9,989 million. Customer deposits fell $79.9 million (0.8%), to $9,660 million, due to reductions in checking and savings accounts, partially offset by higher fixed-term deposits. The total rose because the bank increased its brokered loans and deposits by $131.1 million as part of its liquidity management, meaning to ensure it has enough cash on hand.
Credit. The share of loans that stopped being repaid (nonperforming) fell to 0.74%. Payment delinquencies rose due to seasonal factors, though they remain below 2025 levels.
Expenses. Non-interest expenses decreased $6.6 million, to $96.3 million, primarily because certain charges from the prior quarter were not repeated.
This content was translated with the assistance of Artificial Intelligence (AI).